
“We did not set out to build another health insurance company,” said Ty Wang, co-founder and chief executive of Angle Health. The aim, he told the Wall Street Journal, was to stop “this kind of death spiral of cost within our healthcare system.”
His company has just raised $600m at a $2.7bn valuation. Vitruvian Partners led it. The growth investor keeps its headquarters in London.
The timing is not accidental. American employers face the largest jump in health insurance costs in twenty years, and small firms carry the worst of it.
Angle Health sells health cover to American small businesses. It says it now serves more than 5,000 employers across 47 states, some with as few as two staff.
Most of the round priced below the headline
The $600m is not one cheque. Angle Health’s own announcement splits it into a $200m Series C and a $400m tender offer.
The tender offer is the larger part, and it is not new money for the company. It buys shares from existing holders, giving early backers a way out.
The company puts a single $2.7bn figure on the whole thing. The Wall Street Journal, which broke the deal an hour before the release went out, reports that the $400m secondary priced at $2.5bn.
That gap is worth noting. The headline valuation applies to the fresh capital, not to the two thirds of the round that changed hands between investors.
Wang also says the company was not looking to raise. It had little debt and was already growing, and the round arrived less than ten months after its Series B. Other founders have made the same claim this year.
Two Palantir engineers who met at school
Wang and chief technology officer Anirban Gangopadhyay founded the company in 2019. It began trading in 2021.
The pair met as high-school students on the Stokes Educational Scholarship programme, a US government scheme that funds college places for students heading into national security work. They later worked together at Palantir.
They say they built it to close one gap. Staff at small firms get less than staff at large technology companies.
“Access to great healthcare shouldn’t depend on the size of the company you work for,” Wang said in the announcement.
What it actually sells
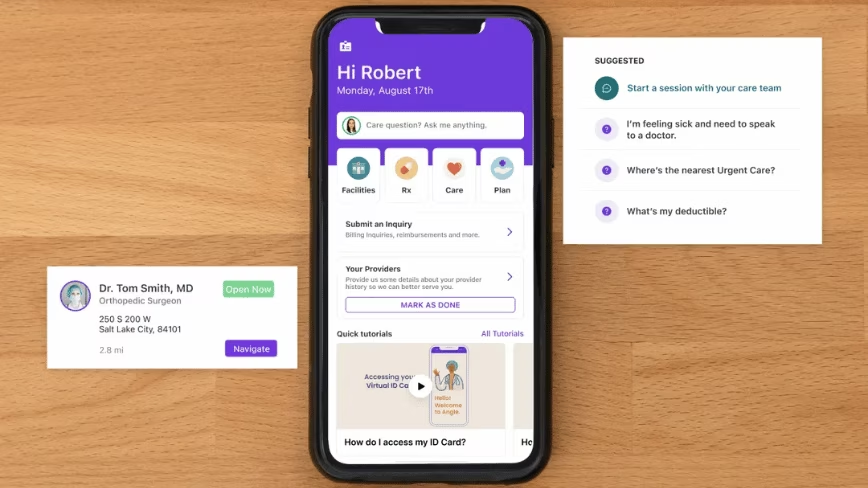
The product is a benefits platform with underwriting attached. Brokers use a tool called Benefit Builder to generate firm quotes in minutes from a staff census, then adjust plans in real time.
The company describes itself as the first AI-native healthcare benefits platform. Its system steers members towards cheaper settings for the same treatment.
Examples it gives include at-home infusions, free-standing imaging centres rather than hospital departments, and international prescription sourcing. Jeremy Gelber, the Vitruvian partner who led the deal, framed the advantage as volume of options.
“Because of AI, they’re able to manage thousands of different designs,” Gelber said.
Two other tools sit alongside it. Quote-to-Card handles implementation, and a Health Scorecard rates plans, which the company calls a first for group underwriting.
Angle Health has also signed care delivery partnerships. Those cover high-cost medications, infusions, outpatient surgery and radiology. The company says the arrangements cut cost without cutting quality.
Several European benefits platforms are chasing the same administrative layer, though none underwrites its own cover.
The numbers the company is claiming
Angle Health reports 120% year-on-year growth and four consecutive quarters of profitability, on both an EBITDA and a net income basis. It oversees close to $1bn in annualised premium equivalents.
Its customer count and revenue both more than doubled in the most recent year, according to the WSJ.
The figure it leans on hardest is renewal pricing. It says median increases for its customers run at 5% to 7%.
It contrasts that with an 18% median for small and midsize businesses, citing a June 2026 study by Morgan Health, a JPMorganChase unit. Consulting firm WTW projects an 11.1% rise in US employer healthcare costs in 2027, the steepest in more than two decades.
Every one of those figures comes from the company. Nobody has independently audited them. A profitability claim from a firm carrying insurance risk reads as a statement of position rather than a settled fact.
The company frames the opportunity around who employs Americans. Small businesses employ close to half the US workforce, and federal data has shown their headcount growing faster than that of larger firms.
The investor is the part that travels
The buyer list is the reason this matters outside the United States. Vitruvian Partners runs more than $23bn in active funds from offices including London, Munich, Madrid, Stockholm and Luxembourg.
Its portfolio is a roll call of European exits: Skyscanner, Just Eat, Wise, Darktrace, Global-e and EasyPark. It also backed Hinge Health, which gives it a route into the same American employer-benefits market.
European growth funds have spent the year raising larger vehicles, and the question has been where that money goes. Here a European firm has written the anchor cheque into a US healthcare business at $2.7bn.
New investor Town Hall Ventures joined the round. Andy Slavitt co-founded that firm. He held health policy roles under Barack Obama and Joe Biden.
Existing backers Blumberg Capital, Portage Ventures, PruVen Capital and Y Combinator all took part. Portage led a $134m round in December, and the WSJ reports the new mark more than doubles that valuation.
The deal closes later this month, the company says. European insurtech has produced its own unicorns this year, though none yet at this scale in health cover.
Get the TNW newsletter
Get the most important tech news in your inbox each week.


